Last reviewed by Manish Kumar: October 26, 2026. Facts were checked against the primary sources listed at the end of this article.
“The bank offered me mortgage insurance when I signed. Is that the same as life insurance?” I hear this from new homeowners all the time, often right after a renewal or a move. They aren’t the same, and the difference can matter a great deal to your family.
The short answer
- Mortgage life insurance is optional coverage, usually offered by your lender, that may pay off your mortgage balance to the lender if you die. The benefit generally falls as your balance falls, while the premium generally stays the same.
- Personal life insurance (term or permanent) pays the amount you choose to the beneficiary you name, who can use it for the mortgage or anything else. It isn’t tied to your lender.
- The Financial Consumer Agency of Canada (FCAC) says term or permanent life insurance may provide better value than mortgage life insurance, because its death benefit doesn’t decrease over the term of the policy.
- Neither is mortgage default insurance (such as CMHC insurance), which you must buy if your down payment is under 20% and which protects the lender, not your family.
- Mortgage life insurance can still suit someone who wants simple, mortgage-only protection and understands its limits. Compare the certificate and the policy, not just the monthly price.
Is there such a thing as mortgage life insurance?
Yes. Mortgage life insurance is a type of credit or loan insurance that lenders usually offer when you take out or renew a mortgage. FCAC is clear that it’s optional: you don’t need to buy it to be approved for a mortgage, the lender can’t insist that you buy it, and you must give your express consent (FCAC, Optional mortgage insurance products).
When a lender offers it, FCAC says the lender must tell you about the charges, get your express consent and give you the option to cancel. Banks must also give you a separate disclosure statement before you consent (FCAC, Mortgage life insurance: know your rights). Lenders may also offer mortgage disability and critical illness coverage, which can make mortgage payments if you can’t work because of a severe illness or injury.
What is CMHC insurance, and how is it different?
CMHC insurance is mortgage loan insurance, also called mortgage default insurance. It’s a completely different product. CMHC explains that if your down payment is less than 20%, you’ll need mortgage loan insurance, and that it protects your lender in case you can’t make your payments (CMHC). Your lender pays the premium and will likely pass the cost on to you, either as a lump sum or added to your mortgage.
Default insurance does nothing for your family if you die. That’s the job of mortgage life insurance or personal life insurance.
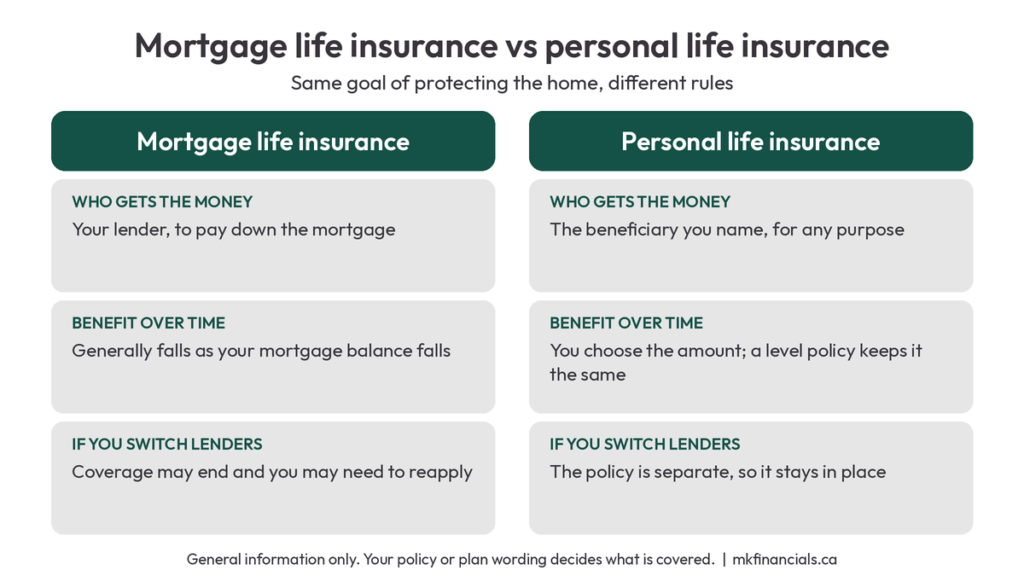
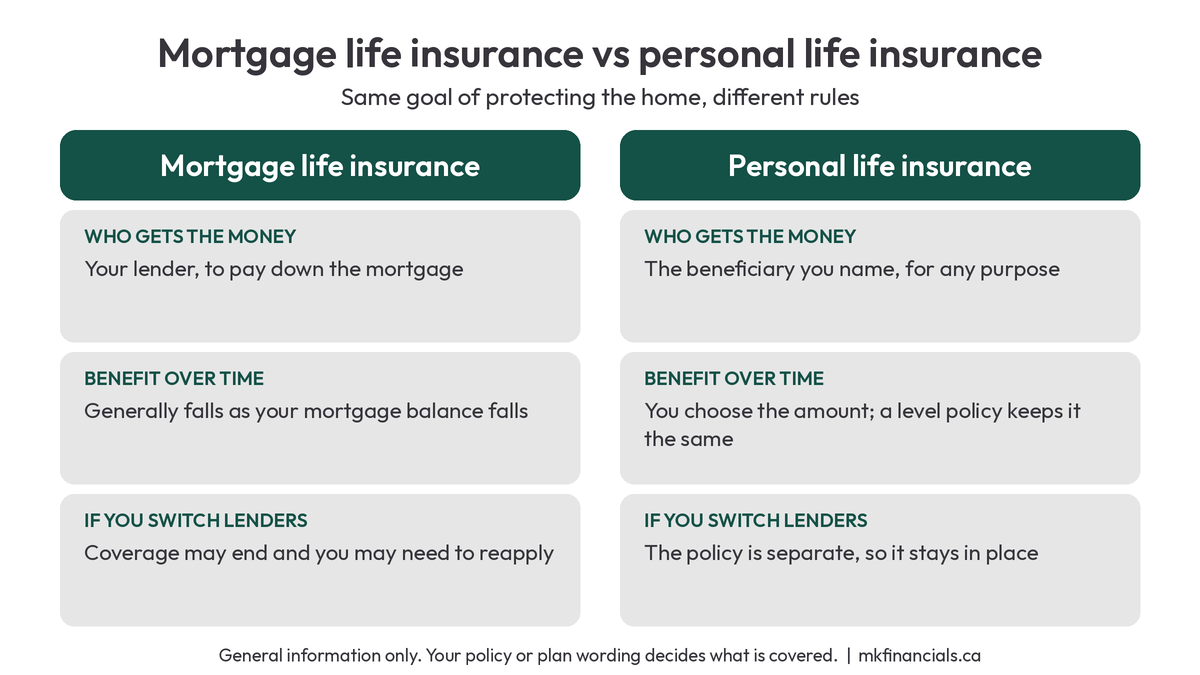
The key differences at a glance
| Mortgage life insurance | Personal life insurance | |
|---|---|---|
| Who gets the money | The lender is the beneficiary and receives the death benefit | The beneficiary you name |
| Benefit amount | Equal to your outstanding mortgage balance, so it decreases as you pay down the mortgage | The amount you choose. It stays the same while the policy is in effect |
| Premiums | Based on your age and mortgage amount when you apply, and generally stay the same as the balance falls | Based on age, gender, medical history and coverage amount. They may be fixed or increase with age, depending on the policy |
| Use of the money | Must be used to pay off the mortgage | The beneficiary may use it for any purpose |
| Application | Often a short yes-or-no health questionnaire. The insurer may approve right away or ask for a medical exam | Usually reviewed by underwriting before the policy is issued |
| If you refinance or switch lenders | Coverage is tied to that mortgage and may end, depending on the certificate | The policy is separate from the mortgage, so a lender change doesn’t cancel it |
The first four rows follow FCAC’s own comparison table (FCAC). Your certificate or policy is the contract that controls the actual result.
Why the same premium can buy a smaller benefit
The decreasing benefit is one of the clearest differences. FCAC confirms that as you pay down your mortgage, mortgage life insurance covers a smaller amount, while the premiums generally remain the same.
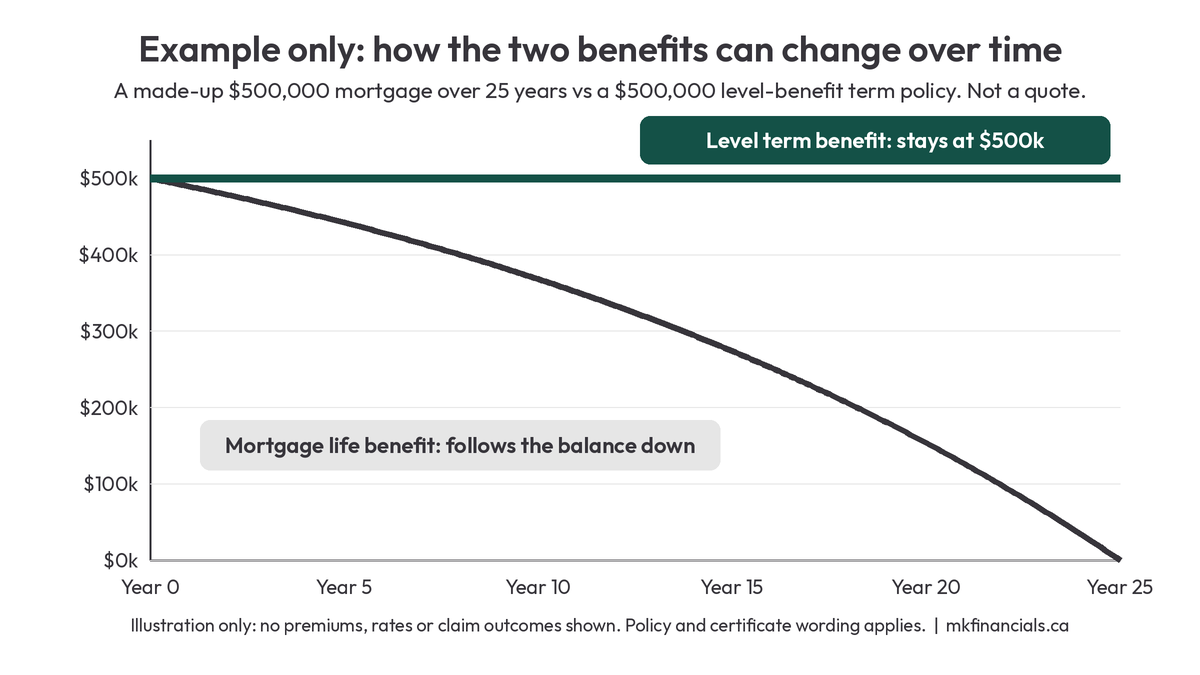
Example only. This is a made-up household to show how the two benefits can change. It isn’t a quote, a recommendation or a real client, and it doesn’t compare premiums.
Nadia and Chris buy a home in London, Ontario with a $500,000 mortgage. They’re offered mortgage life insurance at signing. They also look at a $500,000 level-benefit personal term policy.
Ten years later, their balance has fallen to roughly $300,000. If the mortgage life coverage is based on the outstanding balance, the most it would pay the lender is about $300,000. If the term policy is still in force and a claim is approved, it would pay the full $500,000 to the named beneficiary, who could pay off the mortgage and still have about $200,000 for childcare, income or other debts.
The point isn’t that one is always better. It’s that comparing them only by the starting coverage can be misleading.
The underwriting and claim-time difference
It’s tempting to say bank mortgage insurance has “no underwriting.” That’s too broad. FCAC explains that for credit or loan insurance, applicants usually answer a short series of yes-or-no health questions. Based on the answers, the insurer may approve you right away or ask for a medical exam (FCAC, Credit or loan insurance).
FCAC also warns that your insurance won’t be valid if you don’t answer the questionnaire accurately, and that an insurer may not pay if you had a pre-existing condition related to the claim or had symptoms when you applied. At claim time, the insurer may ask for claim forms, more information or a medical exam. That’s why it’s worth asking, in writing, whether your coverage is fully approved or still subject to review.
With personal life insurance, the review usually happens before the policy is issued. FSRA explains that an individual application goes to underwriting, where the insurer assesses the risk and decides whether the policy can be issued on the terms you asked for (FSRA). That gives you more clarity up front, but it still isn’t a promise of payment. Inaccurate answers, exclusions and policy terms can affect any claim.
Want to compare your bank coverage with a personal policy? Bring your certificate. I’ll compare the benefit, underwriting and cost side by side and explain the differences in plain language, with no pressure to buy.
What are the downsides of mortgage insurance?
Mortgage life insurance isn’t a bad product, but it has trade-offs to understand before you sign:
- A shrinking benefit for the same premium. You pay for coverage tied to what you still owe, not a fixed amount your family controls.
- The lender gets the money. Your family can’t choose to use it for income, childcare or other debts instead.
- It’s tied to one mortgage. If you refinance, transfer or switch lenders, the coverage may end and you may need to reapply at an older age and with your current health.
- More of the review can happen at claim time. A short questionnaire at signing doesn’t always mean eligibility was fully assessed.
- You might not need it. FCAC reminds borrowers to check whether existing coverage through an employer or another policy already meets their needs, and notes that a home can be sold to pay back the mortgage.
At what age does mortgage insurance stop?
It depends on the certificate. FCAC says credit and loan insurance usually has a maximum age to qualify, often between 65 and 70, and that you may lose coverage in some situations, such as owing payments that are past due. Because the coverage is tied to the insured mortgage, it also matters what happens when that mortgage is paid off, refinanced or moved. Check your certificate for the maximum age, when coverage ends and the cancellation steps. You can cancel credit or loan insurance at any time, according to FCAC.
A personal term policy ends on a date set in the policy, such as after 20 or 30 years, and some policies can be renewed or converted. Compare those dates with your amortization, not just your current mortgage term.
When mortgage life insurance may still fit
It can be reasonable when your goal is narrow: clear the mortgage if an insured borrower dies. The application is convenient, the premium is added to your mortgage payment, and some people value the short questionnaire. FCAC notes it can be useful if a spouse or dependants would like to stay in the home but might not manage the same payments.
Before you choose it, ask: Has my eligibility been fully assessed? Does coverage end if I refinance, transfer or pay off this mortgage? What happens with two insured borrowers after one claim? Our mortgage protection options page can help you prepare those questions.
When personal life insurance may fit better
Personal coverage is often the stronger starting point when the mortgage is only one part of what your family would need. Paying off the home lowers monthly costs, but it doesn’t replace income, pay for childcare or fund education. A personal policy lets your beneficiary decide what to pay first, and it stays in place if you shop for a better mortgage rate or move.
The trade-off is usually a more detailed application. Age, health, smoking status and occupation can affect eligibility and price. In my experience with Ontario homeowners, many choose a term life insurance policy whose length roughly matches their amortization, then review it when they refinance or pay down the mortgage.
Your checklist before you decide
- Add up what your family would need. Include the mortgage, income replacement, childcare, education and final expenses. The life insurance needs calculator can help.
- Compare benefits over time, not just on day one. A declining benefit and a level benefit can look the same at signing.
- Ask what underwriting is complete before your first premium, and what may be reviewed at claim time.
- Check refinancing and lender-switch rules. Find out whether coverage ends, transfers or needs a new application.
- Don’t cancel anything early. Keep existing coverage until a replacement policy is issued, delivered and in force.
So, which should you choose?
Personal life insurance is often the stronger starting point if you want a benefit that doesn’t shrink, a beneficiary who controls the money and coverage that doesn’t depend on your lender. Mortgage life insurance can still fit when convenient, mortgage-only protection matches what you need and you understand its declining benefit and refinancing rules. Whether you live in Ontario, Alberta, BC, Quebec, New Brunswick, Nova Scotia or Manitoba, the right choice comes from the coverage your household needs and the terms you can actually get.
Frequently asked questions
1. What is the difference between mortgage insurance and life insurance?
Mortgage life insurance pays your outstanding mortgage balance to the lender if you die, and the benefit generally decreases as you pay down the mortgage. Personal life insurance pays the amount you choose to the beneficiary you name, who can use it for any purpose, and the benefit stays the same while the policy is in effect.
2. Is there such a thing as mortgage life insurance?
Yes. It’s optional credit insurance that lenders usually offer when you take out or renew a mortgage. FCAC says you don’t need to buy it to be approved for a mortgage, and the lender must get your express consent.
3. What is CMHC insurance?
CMHC insurance is mortgage loan insurance, also called default insurance. You need it if your down payment is less than 20%. It protects your lender if you can’t make your payments. It doesn’t pay anything to your family if you die.
4. What are the downsides of mortgage insurance?
The benefit generally shrinks as your balance falls while the premium stays the same, the lender receives the money, coverage is tied to one mortgage and may end if you refinance or switch lenders, and more of the eligibility review may happen at claim time.
5. At what age does mortgage insurance stop?
It depends on your certificate. FCAC says credit and loan insurance often has a maximum age to qualify between 65 and 70, and coverage generally ends when the insured mortgage is paid off. Check your certificate for the exact termination age and rules.
6. Is personal life insurance better than mortgage insurance?
Not in every case, but FCAC says term or permanent life insurance may provide better value because the death benefit doesn’t decrease over the term of the policy and your beneficiary can use the money for any purpose. Compare actual quotes and contracts for your situation.
7. Can I cancel mortgage life insurance?
FCAC says you can cancel credit or loan insurance at any time, usually by contacting the insurance company first. Before cancelling, make sure any replacement coverage has been approved and is in force.
If you’d like help comparing the benefit, underwriting and cost side by side before you replace any existing coverage, I’m happy to help.
This article is general information only and isn’t financial, insurance, tax or legal advice. Coverage, definitions, exclusions and costs vary by insurer, policy and personal circumstances, and the policy wording always applies. MK Financials works with Experior Financial Group as its managing general agency (MGA). Insurance policies are issued by the respective insurance companies.
Sources
- Financial Consumer Agency of Canada, Optional mortgage insurance products
- Financial Consumer Agency of Canada, Mortgage life insurance: know your rights
- Financial Consumer Agency of Canada, Credit or loan insurance
- Canada Mortgage and Housing Corporation, What is CMHC mortgage loan insurance?
- Financial Services Regulatory Authority of Ontario, Working with a life and health insurance agent or company